Treasury, Cash & Banking
Payments Fraud Is High. Recovery Is Getting Harder.
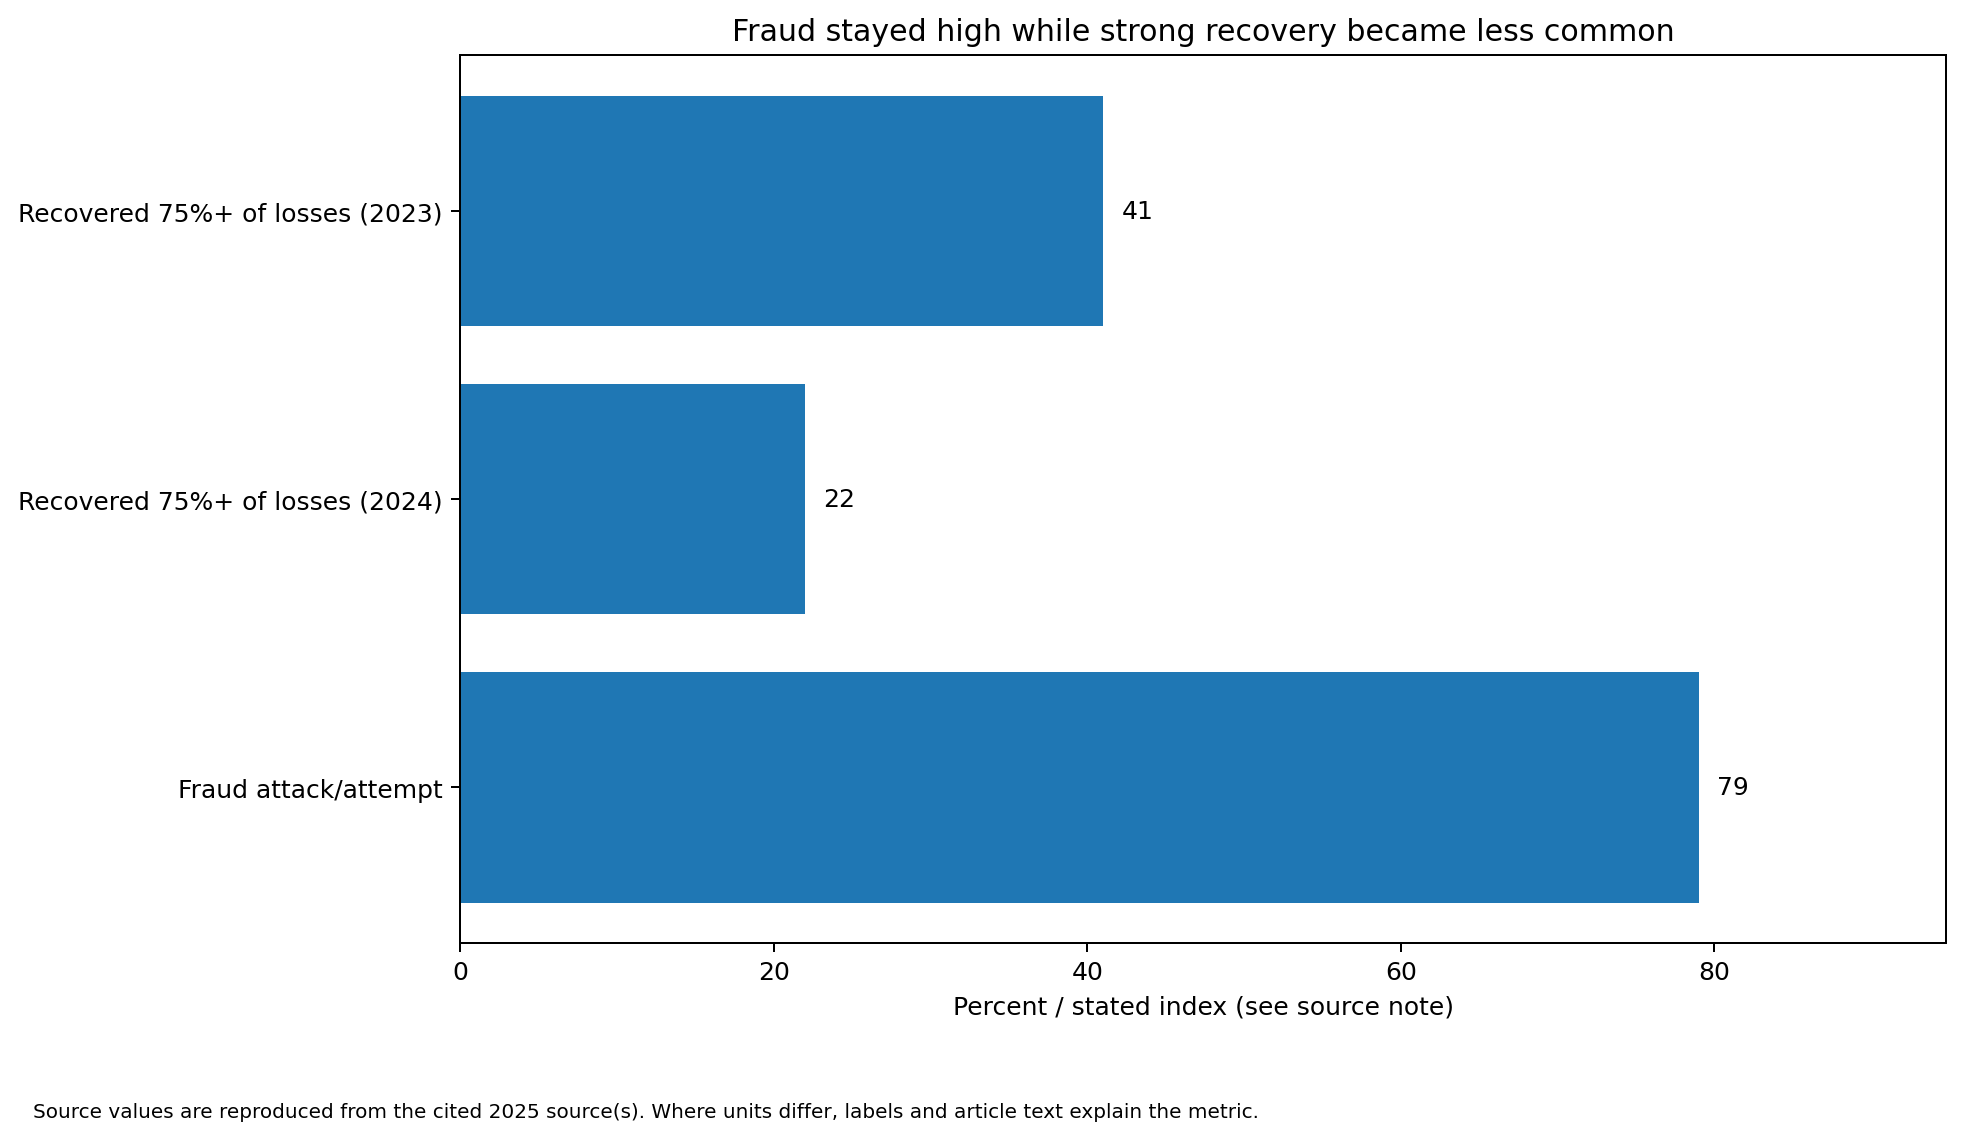
AFP’s 2025 fraud benchmark showed attempted or actual fraud at 79% of organizations, while only 22% recovered at least three-quarters of lost funds—down sharply from the prior survey. Treasury’s control case is shifting from prevention alone to verification, response speed and recoverability.
For Treasurer · AP Leader · Controller · CFO
Level All Levels
AFP’s 2025 fraud benchmark showed attempted or actual fraud at 79% of organizations, while only 22% recovered at least three-quarters of lost funds—down sharply from the prior survey. Treasury’s control case is shifting from prevention alone to verification, response speed and recoverability.
The useful way to read this story at the end of 2025 is not as another technology headline or survey statistic. It is evidence that the Office of the CFO is changing where work happens, who owns the decision and what has to be controlled. The specific numbers matter, but the managerial implication matters more: finance teams are being asked to move faster without lowering the standard for accuracy, auditability or economic judgment.
What the 2025 evidence actually says
Verified finding 1. 79% reported attempted or actual payments fraud.
Verified finding 2. 22% recovered 75% or more of funds lost to fraud in 2024, versus 41% for 2023.
Verified finding 3. Wire transfers reclaimed the top spot among payment types targeted by BEC.
Verified finding 4. Vendor and third-party impersonation remained prominent BEC tactics.
These findings should be read within the scope of their underlying surveys, product announcements or case evidence. Vendor claims are not treated as independent benchmarks, and survey associations are not treated as proof that one practice caused another outcome.
Why this deserves attention now
The finance function has spent much of the last decade digitizing individual activities. In 2025 the pressure moved toward the connections between them. Planning depends on trusted data. Accounting automation depends on clean process design. Procurement risk reaches treasury through payments. Billing architecture affects revenue recognition and collections. AI depends on governed business definitions.
That interdependence changes the economics of transformation. A local improvement can be real and still fail to improve the end-to-end process if the next handoff remains manual, ambiguous or poorly controlled. CFO organizations therefore need to evaluate change at the workflow level rather than by counting features deployed.
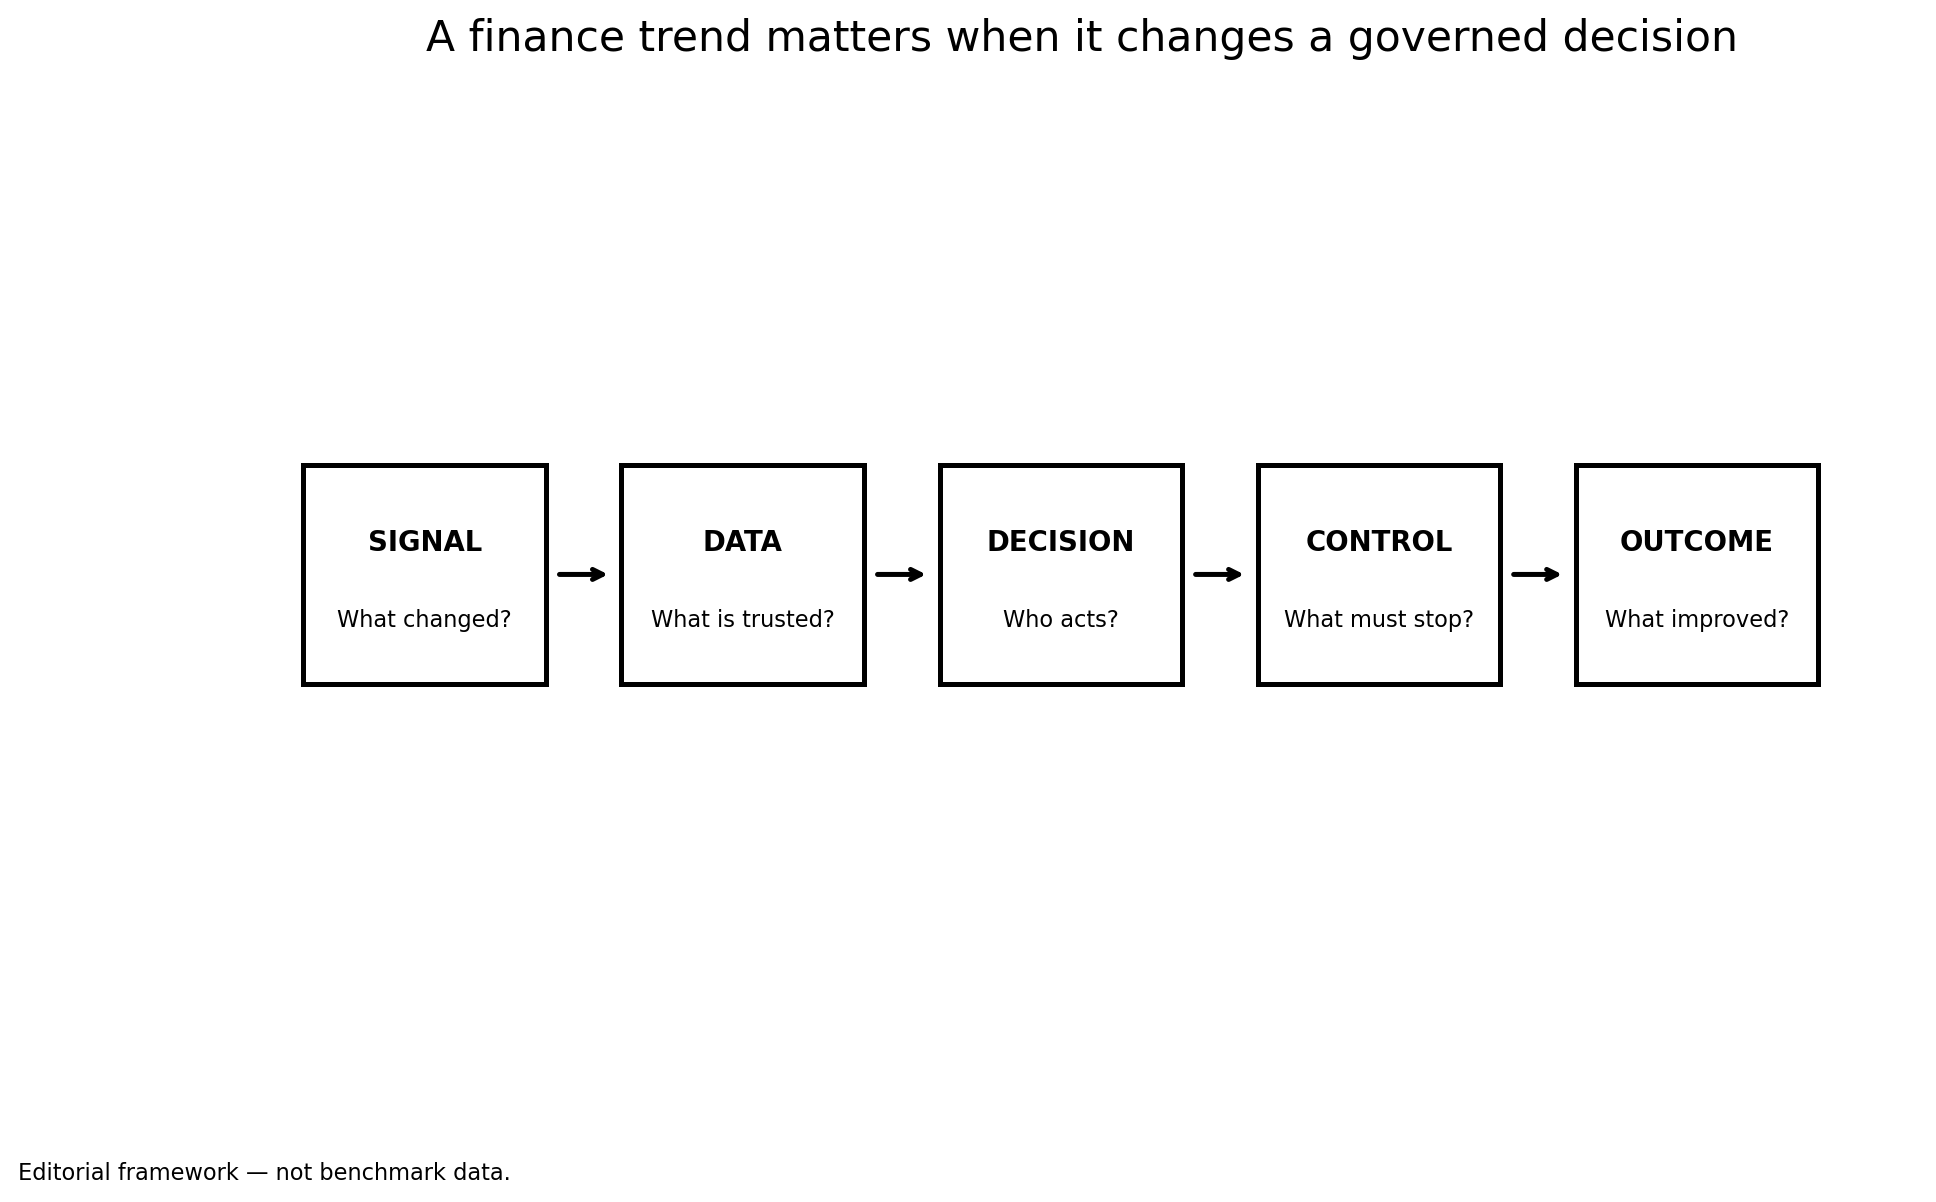
For practitioners, the practical question is simple: what decision becomes better, faster or safer because of this change? If that question cannot be answered, the initiative may be technically impressive without being financially important.
The control question is becoming inseparable from the productivity question
Finance cannot adopt the same definition of speed as a consumer application. A forecast, journal, supplier change, credit decision or cash movement becomes valuable only when users can understand where the information came from and who remains accountable.
That makes control design part of product design. The right workflow does not merely automate a step. It defines evidence, thresholds, exceptions, approvals and escalation. As AI and automation move closer to execution, those boundaries become more important.
A useful test is to divide the process into four layers: observation, recommendation, preparation and execution. Finance can often automate observation aggressively. Recommendation requires validation. Preparation can be automated when evidence is retained. Execution should depend on materiality, authority and risk.
What managers should change
Managers should start with the process rather than the software. Map the current handoffs, identify the slowest decision and separate genuine judgment from administrative work. Then decide which data definitions must be common across the process.
Next, create a small set of outcome measures. Cycle time is useful, but it is not enough. Add exception rates, rework, control failures, decision latency and the amount of senior-finance capacity consumed by routine production.
Finally, define ownership after automation. If a system drafts the answer, someone still owns whether the answer is economically and technically correct. That accountability should appear in the operating model, not remain an informal expectation.
What controllers and CFOs should be skeptical about
The 2025 market produced a large amount of confident language about autonomous finance, continuous planning, intelligent procurement and agentic workflows. Buyers should distinguish availability from adoption and adoption from proven value.
A feature in preview is not the same as a production control environment. A vendor-reported customer outcome is not a market benchmark. A survey showing that higher-performing organizations use a practice more often does not establish causation.
Finance leaders should ask for evidence that matches their environment: transaction volume, entity complexity, regulatory requirements, ERP architecture, data quality and staffing model.
The architecture underneath the headline
The most durable change is often less visible than the application interface.
Finance increasingly needs a common layer of definitions, permissions and process state that can be used by people, analytics and AI. Without it, every new tool creates another interpretation of customer, revenue, supplier, cash or margin.
This is why data governance and workflow governance keep reappearing across seemingly unrelated finance stories. The issue is not centralization for its own sake. It is creating enough consistency that automation can scale without multiplying reconciliation work.
A practical 90-day response
Finance teams do not need a multi-year program to act on this trend. Pick one high-friction workflow and establish a baseline. Document the current cycle time, manual touches, data sources, exceptions and control points.
Then redesign only the part that creates the largest delay or risk. Use existing technology where possible. Test with real users. Require evidence for every automated decision. Measure whether the process improved.
If it works, standardize the pattern before expanding it.
That sequence—prove, control, standardize, scale—is less dramatic than a transformation announcement. It is also more likely to survive the next budget cycle.
What 2025 changed
The year did not eliminate the old finance constraints. Spreadsheets remained pervasive. Experienced talent remained uneven. Data quality remained a problem. Fraud remained high. Economic and trade uncertainty complicated planning.
What changed was the cost of leaving those constraints disconnected.
The strongest finance organizations are beginning to treat data, process, technology, controls and talent as one operating system. That is the buyer-and-leadership lesson behind this story.
For Treasury, Cash & Banking leaders, the implication is not to chase every 2025 trend. It is to identify which trend changes the economics or risk of a process they already own—and redesign that process deliberately.
That is where the headline becomes finance value.
Key takeaways
- Treasury leaders
- Prevention alone no longer describes the risk: with strong recovery reported far less often for 2024 than 2023, response speed and recoverability belong in the control design.
- AP and payments teams
- Wire transfers were again the top payment type targeted by BEC, and vendor impersonation stayed prominent — verification of bank-detail changes is a payment control, not an administrative step.
- CFOs
- Survey findings describe their own sample; test the 79% and 22% figures against your own payment mix, entity structure and banking arrangements before assuming they apply.
Sources & further reading
- AFP2025 Payments Fraud and Control Survey79% reported attempted or actual payments fraud; 22% recovered 75%+ of funds lost in 2024 versus 41% for 2023; wire transfers top BEC-targeted payment type
Survey findings are reported within the scope of their underlying samples, and associations are not treated as causal proof. Vendor statements are identified as vendor-reported and are not treated as independent benchmarks. The signal-to-outcome diagram is a The Finance Observer editorial framework, not benchmark data. Only information publicly available on or before December 31, 2025 is used, and no quotes are invented.
- Topics
- Treasury, Cash & Banking
- For
- Treasurer · AP Leader · Controller · CFO
- Level
- All Levels
About the author
Ethan ColeTreasury & Payments Correspondent
Ethan covers corporate treasury, cash management and banking, with a focus on the technologies and practices changing how finance teams manage liquidity, payments and financial risk.
The Finance Observer content is for informational purposes only and is not professional financial, tax, legal or investment advice.
Related reading
The Always-On Treasury Is Arriving. Cash Management Was Not Designed for It.
FedNow settled almost five million payments in Q2 2026, up 83%, and the network limit is now $10 million. The real prize is not faster vendor payments — it is rethinking prefunding, liquidity buffers and controls.
The Fed Is on Hold, but Treasury’s Rate Problem Is Getting Harder
The FOMC held at 3.5%–3.75% in July, but by September 4 the 30-year Treasury yield sat 133 basis points above the three-month. Cash, refinancing and hedging no longer move as one trade.
Treasury Is Becoming a Real-Time Control System
Corporate treasury is moving toward connected bank data, continuous cash visibility and AI-assisted forecasting — but faster information makes controls more important, not less.
Related across formats
Curated video and audio that share this article's finance topics.
TreasuryCast
Bank Guarantees Are Still Stuck in Spreadsheets. Treasury Has a Visibility Problem.
Recorded at Treasury 360° Europe, host Eleanor Hill and Surecomp’s Head of Product Achraf Abourida on how fragmented bank portals and spreadsheets obscure guarantee obligations across entities. The guest represents Surecomp, a trade finance technology provider. TreasuryCast is published by TMI.
TreasuryCast
Tokenised Deposits Move From Banking Experiment to Treasury Operations
Host Eleanor Hill with Ant International’s Kelvin Li and HSBC’s Selene Chong and Lewis Sun on using HSBC’s Tokenised Deposit Service to move liquidity between group entities. The speakers represent the provider and its customer; operational benefits are their claims. TreasuryCast is published by TMI.